Bitcoin insights and practical guides
By Crypto Dispensers · Updated November 2, 2026
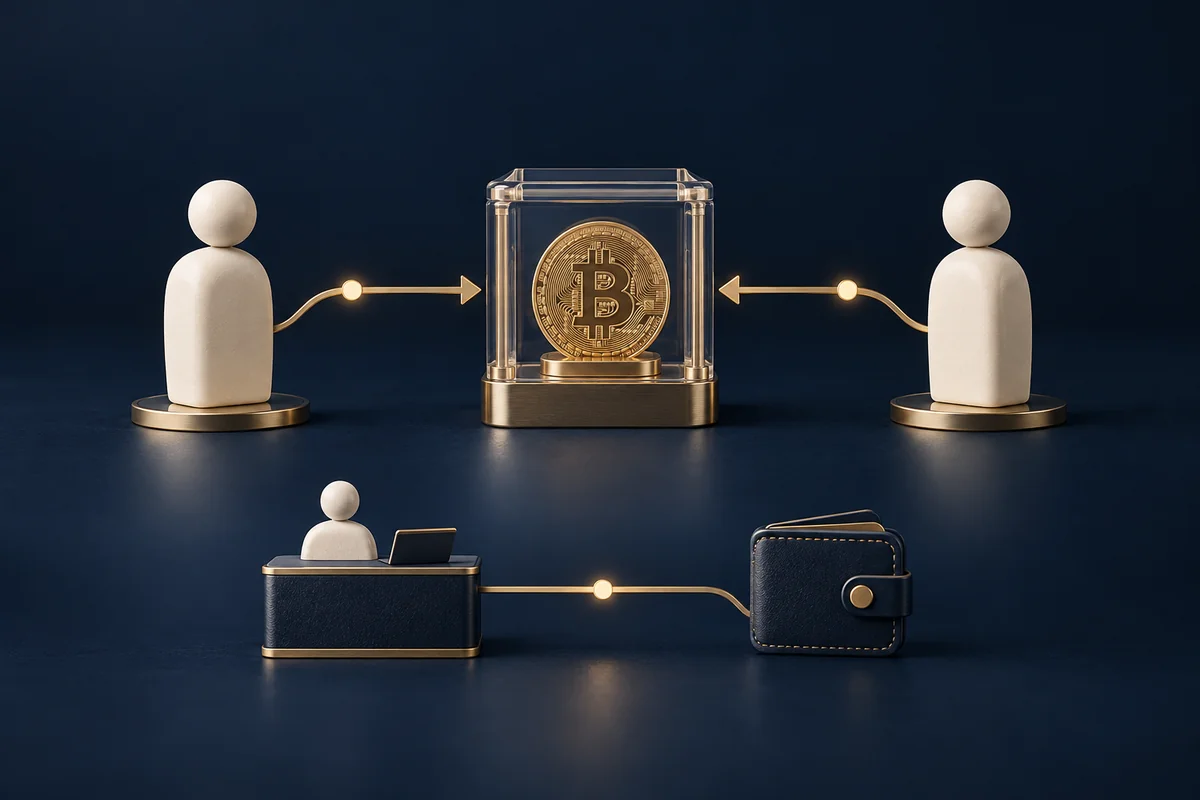
Before paying, know which assets the escrow holds and which evidence the dispute team accepts.
| What to check | How to use it |
|---|---|
| Counterparty changes the recipient | Pause. Do not send to a replacement person or account until the platform confirms what is permitted. |
| Payment sent, release missing | Keep the order open under the platform’s rules, save the payment reference and use its official dispute channel. |
| Someone asks you to move to chat | Keep order instructions and evidence in the platform. Verify support independently before sharing any records. |
Scroll the table to see both columns.
A payment screenshot cannot establish that funds have finally arrived. If you are selling, use your own payment account to check receipt before following release instructions. Escrow, a high rating and a familiar payment method each have limits; understand them before committing.
Practical checks added November 2, 2026. FTC Bitcoin ATM scam guidance · Bitcoin payment and wallet guidance.
Confirm the counterparty, payment terms and supported dispute process.
The bank or payment service moves money separately from the marketplace’s Bitcoin controls.
The agreed escrow or protocol rules determine how Bitcoin is released. They differ by product.
Complete required verification and obtain the instructions for your purchase.
Your bank moves the dollars; our team confirms receipt and required review.
You approve the final quote before we complete the purchase and send Bitcoin to your confirmed wallet.
| Before you pay | P2P offer | Our wire purchase |
|---|---|---|
| Who is on the other side? | The participant named in the agreed trade, under that product’s rules. | Crypto Dispensers is your purchase contact; use our issued bank instructions. |
| Who handles a payment question? | Your bank handles its transfer; the marketplace or protocol has its own support or dispute process. | Your bank handles its transfer; our team handles your purchase request. |
| What authorizes Bitcoin release? | The product’s escrow, signatures or other release conditions. | Funds receipt, required checks and your final-price and wallet approval. |
| Is recovery guaranteed? | No. Read the specific dispute and cancellation rules. | No. Cancellation depends on the purchase stage; contact our team promptly. |
These are different transaction arrangements. Neither description proves that a purchase will be cheaper, faster or free of risk. Read Bisq’s product-specific trading rules as one P2P example, and our wire-transfer process for the service we offer. This comparison does not mean every P2P platform uses Bisq’s model.
Buying from another person
In a peer to peer purchase, you trade with another participant through a marketplace or trading protocol. That can give you more choice over offers and payment methods. It also puts decisions about the counterparty, payment and dispute process directly in your path. A good price does not resolve those decisions for you.
A trade has two sides. A screenshot of one does not prove that both are complete.
01 / Understand the arrangement
Some services hold a seller's Bitcoin during a trade. Other protocols use transaction signatures, deposits or different arrangements. Do not assume every product described as P2P uses the same escrow, or any escrow at all. Find out who can release funds, what both parties must do and what happens when they disagree.
Bitcoin's own peer to peer network is a different concept. It lets participants exchange and verify transactions without making every Bitcoin purchase a marketplace trade between strangers.
Bisq's payment documentation makes a useful distinction: money transfers take place outside its software. Different payment methods carry different reversal, timing and verification risks. A trade interface cannot turn a pending transfer into settled money simply by displaying a reassuring message.
Before choosing an offer, read the current rules for that specific product, version, currency and payment method. Identify the payment deadline, required deposit, withdrawal conditions and dispute route. If you cannot explain how your money comes back after a failed trade, resolve that uncertainty before paying.
In its May 16, 2026 report, Bisq said a May 1 protocol exploit affected Bisq v1 altcoin trades. The report distinguished those trades from fiat trades and said Bisq 2 and Bisq Easy were not affected. Its June 16 update reported reimbursements and further security work. These are dated reports from the project, not a current security certification or a promise of reimbursement for a future loss.
The lesson is narrower than “all P2P is unsafe.” Check incident reports and release notices as well as the feature list. A decentralized design still has code, operating assumptions and failure modes.
02 / Keep evidence separate from persuasion
Compare the recipient and payment details with the agreed trade record. Do not follow a last minute request to pay a different person, switch methods or complete the deal in a private chat. Resolve discrepancies through the documented support process.
Keep the order number, payment reference and messages. Follow the product's procedure to record that payment was sent. If delivery stalls, use its dispute process. Do not send a second payment merely because someone says the first one disappeared.
Check incoming money through your own financial provider, not through a link or image supplied by the buyer. A pending credit or notification may not mean the payment is final. Understand the method's reversal risk before releasing Bitcoin.
Imagine agreeing to buy $200 of Bitcoin, then receiving a message asking you to send the money to the seller's cousin instead. The amount has not changed, but the transaction has. Your original agreement no longer describes the requested payment. Pause and use the official dispute or cancellation procedure before sending money. This is an invented example, not a live offer.
The FTC advises checking recipient information and protecting payment accounts. If you suspect fraud, contact the payment provider through its official app or website promptly and report it to the FTC. A report or dispute does not guarantee recovery. Never disclose a password, verification code or recovery phrase to someone claiming to help.
03 / Decide before opening a trade
Write down the money you will pay and the spendable Bitcoin you expect to receive after applicable costs. Check whether a deposit is refundable, when it becomes available again and whether network or withdrawal charges are additional. A small advertised trading fee can coexist with an expensive exchange rate. For Crypto Dispensers pricing, use your current account quote.
Your counterparty may receive payment account information. Your bank or payment service keeps its own records. Bitcoin transactions are public, and a wallet address can become associated with a person. Do not treat the P2P label as a guarantee of anonymity or as permission to ignore identification requirements.
FinCEN's May 2019 guidance addresses people acting as P2P exchangers in the United States. A person providing covered money transmission services can have registration, compliance and reporting duties even without a formal storefront. The analysis depends on the activity, not just the label. This federal guidance is not a complete statement of state law or another country's rules.
If you plan to buy and sell for others or operate an exchange business, get advice specific to your activity and jurisdiction. For personal cash purchases, our cash purchase legality guide explains several important distinctions.
P2P is one buying route, not a requirement for owning Bitcoin. Compare it with a service whose funding, verification and withdrawal process you understand. Review how to buy Bitcoin safely before choosing where to transact.
04 / Common questions
No. Products and protocols differ. Read the actual custody, deposit, release and dispute rules before placing an order.
No. A rating describes recorded activity within a system. It does not establish that the current payment details, person or transaction are safe.
Do not abandon the documented transaction process for a private promise. The new arrangement may remove evidence or protections you expected to have.
The Bitcoin network does not provide a chargeback service. A refund requires a separate return transaction. A marketplace dispute process has its own limits and cannot promise recovery in every case.
05 / Sources and scope
Reviewed September 18, 2026. Educational guidance, not personalized legal or investment advice. Provider examples explain documented mechanisms and dated incidents; they are not an endorsement, a current availability check or a hands on platform review. Check current official notices before using any service.
Not sure how to pay? Compare wire, ACH, debit card, and credit card purchases. Each has different costs and timing. Ask our team if you need help choosing.
Compare Bitcoin buying options →Published by Crypto Dispensers, which offers crypto buying, selling and swapping services. This article is educational. Bitcoin prices can fall; fees, timing, eligibility and available services vary. Review the applicable terms before you transact.
Your Crypto Dispensers account
Create an account to see the services available to you. You can buy Bitcoin by wire, debit, credit or ACH, sell supported crypto for a USD bank payout, or exchange supported assets. Contact our team if you need help choosing a service.
Creating an account does not authorize a payment. Availability depends on your location, account and required checks.
Helping people access Bitcoin since 2017.
Privacy controls
Necessary cookies are always on so the site works. You can also allow analytics to help us improve the experience, and advertising cookies to measure campaigns and show more relevant ads. You can change this anytime.
Read our privacy policy